 Facebook
 X
 Pinterest
 Copy Link
Could AI Data Centers and a Future SpaceX Project Change Baton Rouge Real Estate?
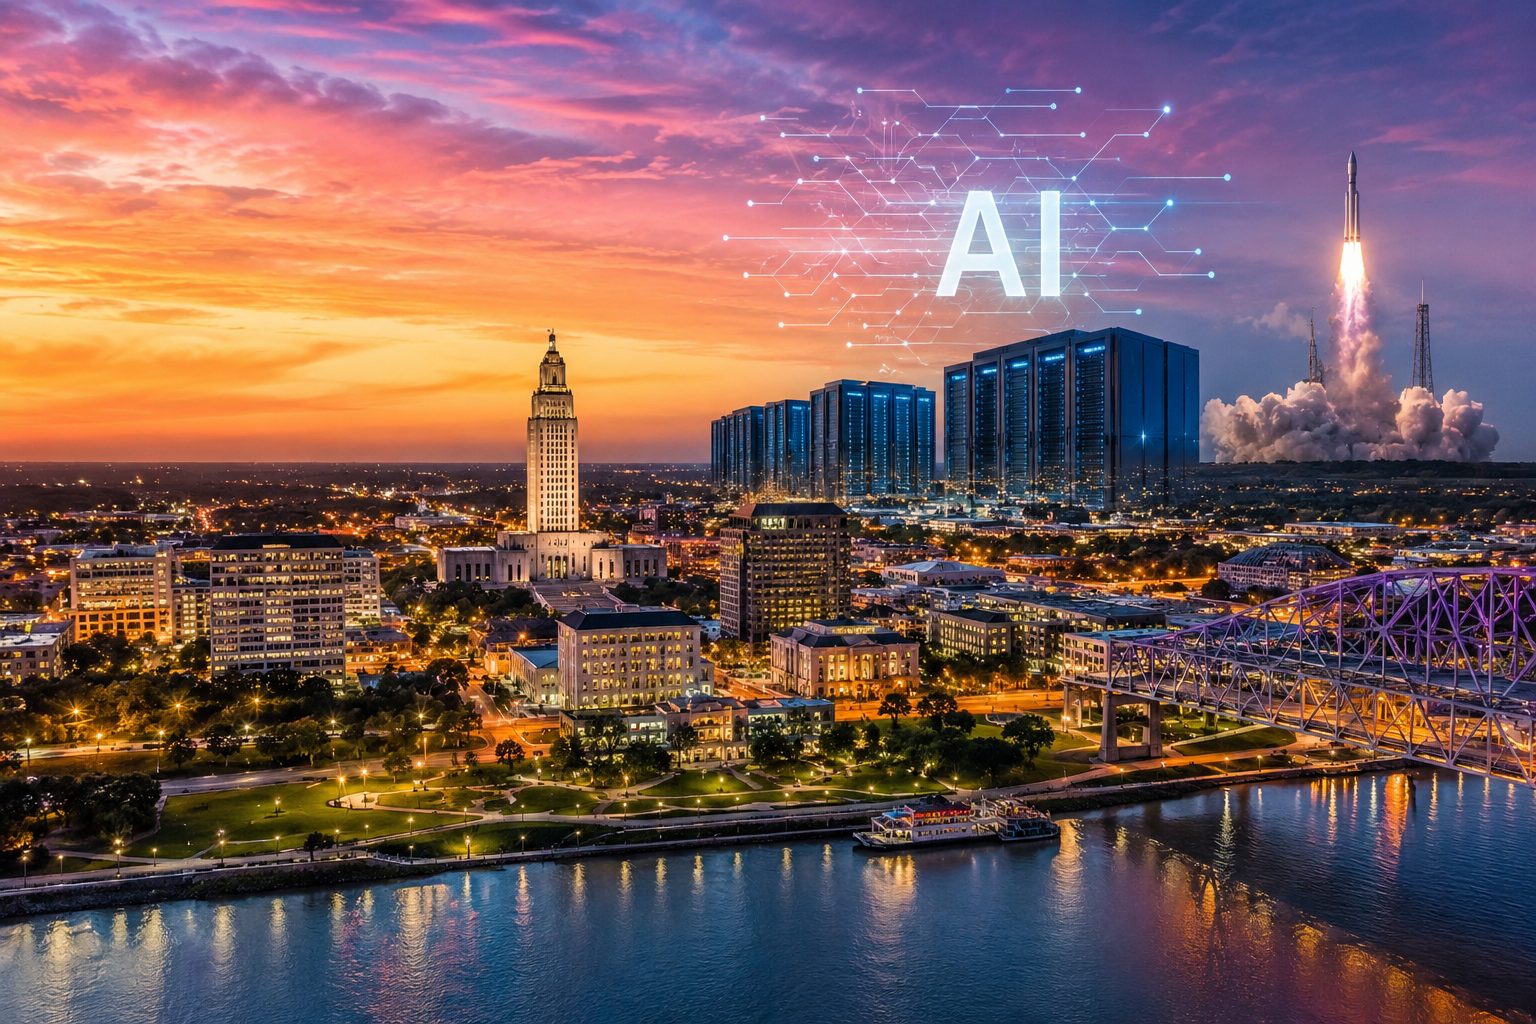
Louisiana is suddenly finding itself in conversations that, until recently, usually centered around Texas, Arizona, and North Carolina. Billions of dollars in AI infrastructure are being announced across the state, and rumors continue to swirl about future aerospace investment. It raises an interesting question for homeowners and investors alike. Could this be the catalyst that changes Baton Rouge real estate?
Every so often, something happens that has the potential to change the direction of an entire region.
For decades, Louisiana has been known for energy, petrochemicals, shipping, and agriculture. Today, another industry is beginning to emerge. Artificial intelligence infrastructure.
Major technology companies have announced tens of billions of dollars in AI data center investments across Louisiana, including projects from Meta, Amazon, Hut 8, and Applied Digital. These projects are spread across the state, but together they represent one of the largest waves of private investment Louisiana has seen in years.
At the same time, rumors continue to circulate that SpaceX may be evaluating parts of coastal Louisiana for future operations. As of today, there has been no official announcement confirming a Louisiana SpaceX project, so that remains speculation and should be viewed as exactly that.
As a real estate agent, I find the bigger question even more interesting.
What could all of this mean for Baton Rouge?
Baton Rouge could benefit even without hosting the projects
One of the biggest misconceptions about economic development is that every benefit stays exactly where the project is built.
That is rarely how growth works.
Baton Rouge already serves as one of Louisiana’s largest employment, education, medical, and business centers. As industries expand across the state, companies often need executives, engineers, attorneys, consultants, suppliers, contractors, financial professionals, and support businesses. Many of those people naturally gravitate toward larger metro areas that offer more housing, restaurants, schools, entertainment, and airports.
That does not mean every new AI employee will move to Baton Rouge.
It does mean Baton Rouge could become an even more attractive place to live while working throughout south and central Louisiana.
Could this finally create momentum for downtown Baton Rouge?
This is where things become interesting.
For years, people have talked about downtown Baton Rouge reaching its potential.
It has beautiful views of the Mississippi River. It has Louisiana’s State Capitol. It has growing restaurants, museums, festivals, and entertainment. Yet many people still feel downtown has never quite reached the level of activity seen in cities like Nashville, Austin, or even parts of New Orleans.
Large scale economic growth often changes that.
More high paying jobs typically create demand for:
- Luxury apartments
- Condominiums
- Hotels
- Restaurants
- Coffee shops
- Retail
- Entertainment
- Office space
People tend to follow opportunity.
Opportunity creates demand.
Demand creates investment.
Investment creates places people actually want to spend time.
That is how many successful downtown districts have evolved over time.
Higher paying industries usually help housing markets
One reason real estate professionals pay close attention to job announcements is simple.
People need places to live.
When an area begins attracting higher paying industries, demand often increases for both homes to purchase and homes to rent. That does not automatically mean prices rise overnight. Interest rates, housing inventory, insurance costs, and the broader economy still matter.
But strong job growth has historically been one of the healthiest long term drivers of real estate demand.
For Baton Rouge, this could benefit neighborhoods throughout the city, from established luxury communities to newer developments.
There are also real challenges
Every major investment brings questions along with opportunities.
Several Louisiana AI data center projects have generated discussion about electricity demand, water usage, infrastructure, and long term utility costs. These are important issues that state regulators, utility companies, and local communities continue to evaluate.
Growth is rarely perfect.
The goal is making sure growth benefits both businesses and the communities where people already live.
My opinion
I believe Louisiana is at an interesting point.
For many years, conversations about major technology investments usually centered around Texas, Tennessee, North Carolina, or Arizona.
Now Louisiana is entering those conversations. That alone changes how people around the country may begin viewing our state.
If Baton Rouge continues improving its downtown, investing in infrastructure, supporting local businesses, and attracting talented professionals, I believe the city could benefit from this momentum even if many of the largest projects are located elsewhere.
Real estate has always been about more than houses. It is about jobs. It is about confidence. It is about whether people believe a city’s best days are ahead of it.
Right now, there are reasons to be optimistic while also staying realistic.
Only time will tell how much of this investment ultimately reshapes Baton Rouge, but it is certainly worth watching.
If you have questions about how these developments could affect your home’s value, investment opportunities, or the Baton Rouge housing market, I would be happy to help. Visit MoveWithMusso.com or reach out to John Musso Real Estate anytime for local insight and thoughtful guidance.
John Musso
5025 Bluebonnet Boulevard, Baton Rouge, LA 70809
(225) 939-8648
MOVE WITH MUSSO
Hurricane and Flood Insurance in Baton Rouge: 2026 Rate Update and How to Shop It Smart
Hurricane and Flood Insurance in Baton Rouge: 2026 Rate Update and How to Shop It Smart
If you own a home in Baton Rouge, or you’re about to buy one, you already know the drill. Insurance isn’t just a line item anymore. For a lot of folks, it’s the line item that decides whether a house is actually affordable.
Here’s a straight-talk update on where hurricane (wind) and flood insurance stand in our market in 2026, and exactly how to shop both without overpaying.
First, the two policies are not the same
This trips up almost every first-time buyer in BR, so let’s clear it up:
- Homeowners insurance covers wind and hail damage from a hurricane, the roof, the windows, the tree that lands on your living room.
- Flood insurance is a completely separate policy. It covers rising water, storm surge, river flooding, flash floods, the kind of water we saw in 2016.
If a hurricane hits and water comes in through the roof, that’s typically your homeowners policy. If water comes in through the front door, that’s flood. Same storm, two different claims, two different policies.
You need both. Especially here.
What the Louisiana homeowners market actually looks like in 2026
The short version: it’s still tight, but it’s better than it was two years ago.
After Ida and the carrier insolvencies that followed, Louisiana lost a lot of insurers. The state’s Insure Louisiana Incentive Program has helped pull some companies back in, and Louisiana Citizens (the insurer of last resort) is no longer the only realistic option for many homeowners in EBR, Ascension, and Livingston parishes.
What this means for you in Baton Rouge:
- More carriers are quoting again, but premiums are still meaningfully higher than pre-2021.
- Wind/hail deductibles of 2% to 5% of dwelling coverage are now standard, not unusual. On a $325K home, that’s a $6,500 to $16,250 deductible before your policy pays a dime on hurricane damage.
- Roof age matters more than ever. Many carriers won’t write a new policy on a roof older than 15 years, and some cap reimbursement to actual cash value (depreciated) instead of replacement cost on older roofs.
Verify locally: exact rate changes, available carriers, and program details shift constantly. Always confirm current numbers with a Louisiana-licensed independent agent before you budget.
Flood insurance and the NFIP’s “Risk Rating 2.0”
FEMA’s National Flood Insurance Program (NFIP) is still the main source of flood coverage in Baton Rouge. Under Risk Rating 2.0, premiums are now based on your specific property: elevation, distance to water, rebuild cost, instead of just your flood zone on the map.
What that’s meant locally:
- Some homes outside the high-risk flood zone (Zone X) saw rates go up because the new model accounts for actual flood risk, not just the FEMA map.
- Some homes inside high-risk zones (AE, A) actually saw rates come down or stay flat, especially newer construction built above base flood elevation.
- Annual rate increases are capped (typically 18% per year for most primary homes), so changes phase in slowly.
Private flood insurance has also grown a lot. For higher-value homes in BR; say Garden District, Highland Road, Country Club of Louisiana, a private policy can sometimes beat NFIP on both price and coverage limits (NFIP caps building coverage at $250,000).
A practical example
Say you’re buying a 2,100 sq ft home in Shenandoah for $310,000.
- Homeowners quotes might range from roughly $2,800 to $5,500+ per year depending on roof age, carrier, and deductible.
- Flood through NFIP might run anywhere from $700 to $2,500+ depending on elevation and zone.
That’s a wide range, which is exactly why shopping matters. The same house, same buyer, can see a $2,000+ annual difference between the first quote and the best quote.
These ranges are illustrative. Get real quotes for your specific address.
How to actually shop it
Here’s the playbook I’d give a friend:
- Use an independent agent, not a captive one. Independent agents in Baton Rouge can quote 10+ carriers at once. Captive agents (one-company shops) can only sell you their product.
- Get at least three homeowners quotes and two flood quotes (one NFIP, one private if you qualify).
- Get an elevation certificate if your home is in or near a flood zone. It can dramatically lower your NFIP premium, sometimes by thousands.
- Ask about the Louisiana Fortify Homes Program. Grants of up to $10,000 are available to retrofit your roof to the FORTIFIED standard, which can unlock insurance discounts on many carriers. Funding is limited and rules change, verify current availability with the Louisiana Department of Insurance.
- Bundle when it makes sense. Auto + home bundles can shave 10–20%, but not always. Run the numbers both ways.
- Re-shop every year. This market moves. The carrier that was the cheapest in 2024 may not be in 2026.
- Don’t shop on price alone. Check the carrier’s AM Best rating (A- or better is a good floor) and read the wind/hail deductible carefully.
Bottom line
Insurance in Baton Rouge is more expensive than it used to be, there’s no sugarcoating that. But the market in 2026 is more competitive than it’s been in years, and homeowners who actively shop (instead of auto-renewing) are saving real money.
If you’re buying, build insurance quotes into your offer process before you go under contract. If you already own, take an hour this month to get fresh quotes. It’s one of the highest-ROI hours you’ll spend all year.
Thinking about buying or selling in Baton Rouge? I’d love to help you run the numbers, including realistic insurance estimates for any home you’re considering. Reach out anytime for a no-pressure conversation about your next move.
John Musso
5025 Bluebonnet Boulevard, Baton Rouge, LA 70809
(225) 939-8648
MOVE WITH MUSSO
 JOHN MUSSO
